
If being an entrepreneur came with a side effect warning label, it might read:
Warning: Running a business may cause sleepless nights, irregular income, minimal vacation time, burnout, and fatigue. Business owners have also reported high levels of independence, deep personal fulfillment, and increases in personal wealth.
Many solopreneurs find it difficult to care for themselves while building and scaling their businesses. The stakes are high, and the risk of failure is ever-present. Mentally, it can be challenging to even consider giving up or doing anything else.
But what if a personal health event caused a week-, month-, or year-long absence from work? Aside from the outcome of the business and the almost certain loss of client work, how much of your own future earnings and income would be lost? How would that change impact your retirement savings?
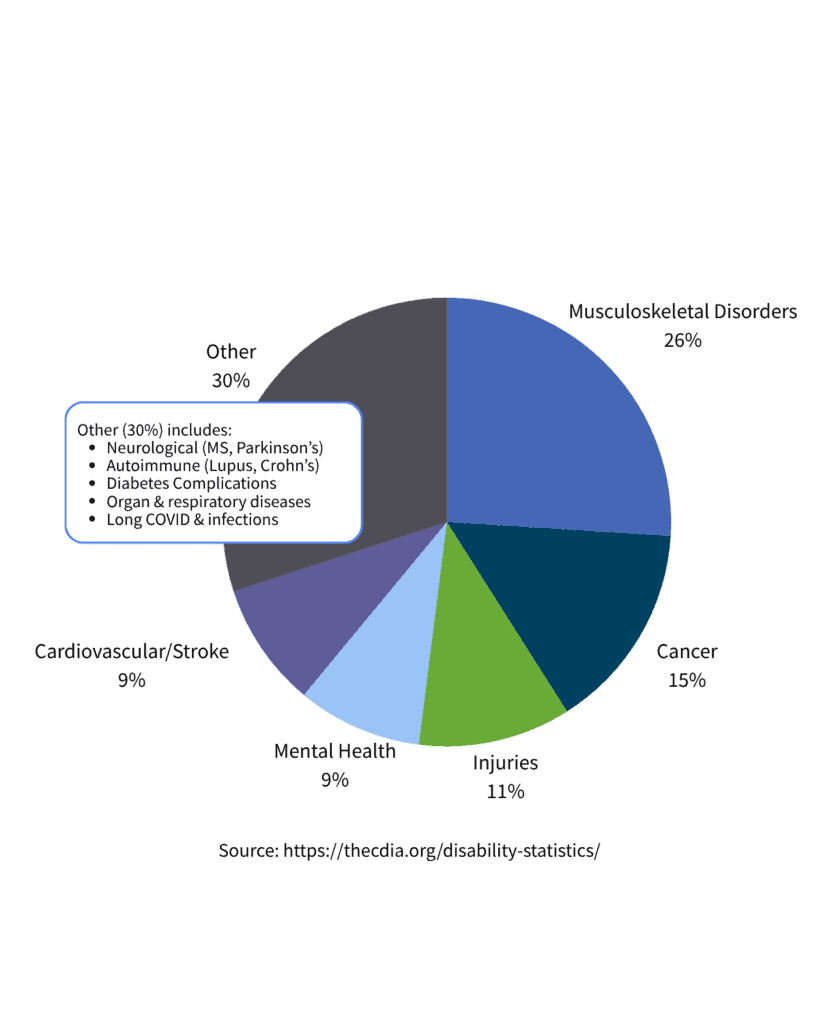
As a solopreneur in their prime earning years, the risk of losing future income is impossible to ignore. Risks cannot be eliminated; they can only be retained or transferred to someone else. In this case, the risk can be transferred to an insurance company. This chart summarizes the common causes of disability. Usually, it is a health event, not necessarily an accident.
What is disability insurance?
Disability insurance is one way to address the potential loss of future income.
A disability insurance policy typically has these features:
- Underwriting is required for most policies.
- The older and unhealthier you are, the more expensive the policy.
- The insurance company will review the type of business, working conditions, and travel.
- A specific benefit amount is payable per month for a number of years (five, for example) or until age 65 if you become disabled.
- Target income replacement is typically 60% of personal income.
- Waiting periods must be satisfied before benefits kick in. 90 days is common.
- Most policies have inflation-adjusted benefits for an additional fee.
What to look for with disability insurance?
For high-income earners, disability insurance companies often limit the amount of coverage they are willing to provide and may not reach a target of 60% income replacement. That’s OK if the goal is to replace enough in income to maintain financial stability. Some insurance carriers will offset the benefits they pay by the amount of Social Security Disability Insurance (SSDI) benefits received while on claim. Same idea for multiple insurance policies — an offset may apply. Look for language in the policies related to other insurance or integration clauses.
Why does tax treatment of disability insurance matter?
In some situations, it may be advantageous to pay premiums personally using after-tax dollars. Benefits from a personally owned disability insurance policy are generally income tax-free if they are not deducted by the individual. If premiums are paid by a business and deducted as a business expense, future disability benefits may be taxable. Consult a tax advisor for more details.
Disability insurance is a risk transfer mechanism and should be evaluated in the context of each person’s objectives. Exercise caution, as some insurance companies may attempt to upsell policies. Greenspring Advisors evaluates insurance needs within the context of your overall financial plan. We do not sell insurance as a fee-only advisor, but we work with trusted third parties to put that coverage into place if needed. If you have questions about the role of disability insurance for yourself or a family member, contact Greenspring Advisors.